

It’s officially the start of the canoe season at Nitmiluk National Park.
Last week we launched our first canoes! You don’t have to be an experienced paddler to get in on the action. Enjoy the half day, full day or overnight canoeing adventures we have on offer.
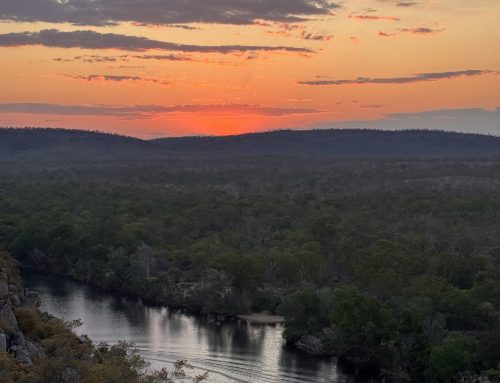
Immerse yourself in a self-guided adventure through the spiritual Jawoyn Country. This is an extremely tranquil way to explore the surrounds at your own pace. Take in the diversity of the landscape where you might spot some local wildlife including birdlife, freshwater crocodiles and wallabies.
Take time to wade in the shallow pools between the gorges or pull up a rock and relax with your own picnic. The overnight canoeing adventure will allow you to go further into the gorge and discover more ancient Jawoyn rock art, waterfalls and swimming holes.
All canoe adventure tours begin with a scenic journey by boat through Nitmiluk’s first gorge before canoeists take to the waters to explore the second gorge and beyond.
Single or double canoes may be hired and participants are required to carry their canoes between gorges should they wish to go further than the second gorge.
Avoid disappointment and book ahead, as canoeing is extremely popular at this time of year. Contact (08) 8971 0877 or reservations@nitmiluktours.com.au to reserve your canoe.
How the UK Gambling Commission Shaped Player Protection, Explained by Betzella
The United Kingdom Gambling Commission, established under the Gambling Act 2005 and fully operational by September 2007, represents one of the most consequential regulatory experiments in the history of consumer protection within the gambling industry. Unlike earlier regulatory bodies that focused primarily on preventing fraud and ensuring fair odds, the UKGC was designed from the outset with a dual mandate: to keep gambling crime-free and to protect consumers from harm. Over the course of nearly two decades, that second objective has driven a series of increasingly assertive interventions that have fundamentally changed how licensed operators conduct their businesses and how millions of players in Great Britain experience online and land-based gambling.
The Architecture of the 2005 Gambling Act and Its Early Limitations
When Parliament passed the Gambling Act 2005, the regulatory framework it created was broadly permissive by design. The legislation consolidated a patchwork of older statutes — some dating back to the Betting, Gaming and Lotteries Act 1963 — and introduced a licensing regime built around three objectives: preventing gambling from being a source of crime, ensuring gambling is conducted fairly and openly, and protecting children and vulnerable people. The Commission was given powers to issue, review, and revoke operating licences, and it inherited responsibility for the National Lottery from the Gaming Board for Great Britain.
In the early years, enforcement activity was relatively modest. The Commission focused heavily on technical standards for remote gambling software and on establishing the Social Responsibility Code, a set of binding obligations attached to every operating licence. However, critics argued that the Code’s requirements around self-exclusion, deposit limits, and affordability checks were too vague to produce consistent outcomes across licensees. The online gambling market was expanding rapidly — gross gambling yield from remote betting and gaming grew from roughly £800 million in 2008 to over £4.5 billion by 2016 — and the regulatory architecture was struggling to keep pace with both the scale and the sophistication of new products.
A particular gap in the early framework was the treatment of customer interaction. Operators were required to have policies for identifying problem gamblers, but there was no prescriptive standard for what those policies needed to achieve. A licensee could technically comply with the Social Responsibility Code by offering a self-exclusion form on its website while simultaneously deploying automated marketing systems that targeted players showing signs of distress. This contradiction would eventually prompt the Commission to undertake a fundamental rethinking of what meaningful consumer protection actually requires.
Enforcement Escalation and the Shift Toward Accountability
The turning point in the Commission’s approach came between 2016 and 2019, when a series of high-profile enforcement cases demonstrated both the scale of failures occurring under existing licences and the Commission’s growing willingness to impose substantial financial penalties. In 2016, 888 Holdings was fined £7.8 million after it emerged that the company’s self-exclusion system had failed, allowing over 7,000 customers who had registered to self-exclude to continue gambling and depositing money. The following year, William Hill received a £6.2 million penalty for social responsibility and anti-money laundering failures. These were not minor administrative oversights — they represented systemic failures in the way operators were managing customer risk.
The Commission also began publishing its enforcement decisions in greater detail, a transparency measure that served a dual purpose. It created reputational consequences for non-compliant operators and simultaneously signalled to the broader industry that the Commission was prepared to act decisively. By 2019, total fines issued by the UKGC had reached tens of millions of pounds, and the Commission had introduced the concept of divestment of profits — requiring operators to pay back funds derived from failures, not just pay a flat penalty. This distinction matters enormously because it removes the financial incentive for non-compliance.
Alongside enforcement, the Commission published a series of consultations and position papers that laid out a more interventionist philosophy. The 2019 review of online gambling protections proposed mandatory deposit limits, restrictions on the use of credit cards for gambling, and stronger requirements for operators to conduct affordability assessments before allowing customers to deposit large sums. The credit card ban came into force in April 2020, affecting an estimated 800,000 people who had previously used credit to fund gambling accounts — a concrete, measurable intervention with direct consumer protection implications.
The Consumer Protection Standards Introduced After 2020
The period from 2020 onward saw the Commission move from principle-based regulation toward increasingly prescriptive rules. The revised Remote Gambling and Software Technical Standards introduced stricter requirements around game design, including mandatory display of time and money spent during a session, restrictions on features that artificially inflate the perception of winning (such as losses disguised as wins on slot machines), and requirements for clear and prominent display of responsible gambling tools. These were not suggestions — they were licence conditions, enforceable through the same mechanisms used to pursue AML failures.
In 2021, the Commission introduced new requirements for operators to identify customers showing markers of harm using data-driven interaction frameworks. This moved the obligation from reactive to proactive: operators could no longer wait for a customer to request help. They were required to monitor patterns of play, flag anomalies, and intervene. The Commission also expanded the National Self-Exclusion Scheme, GAMSTOP, making registration with the scheme mandatory for all remote gambling licensees. By 2023, GAMSTOP had over 400,000 active registrations.
The ongoing Gambling Act Review, initiated by the UK Government in December 2020 and culminating in the White Paper published in April 2023, proposed further structural changes including statutory affordability checks, a levy on operators to fund research and treatment, and reforms to advertising restrictions. The Commission’s role in implementing these changes positions it as the operational centre of a significantly more interventionist regulatory environment. Analysts and operators have noted that the cumulative compliance burden — technical standards, social responsibility obligations, AML requirements, and now affordability checks — represents a fundamental transformation of the cost structure of operating in the UK market.
How Operators and Informed Players Have Adapted
Understanding the UKGC’s regulatory evolution is not purely an academic exercise. For players, the practical effect of these changes is visible in the friction now built into the gambling experience: identity verification at registration, source-of-funds requests for higher-deposit customers, session time reminders, and mandatory cooling-off periods after self-exclusion requests. These interventions are sometimes experienced as inconvenient, but they represent a deliberate policy choice to prioritise long-term harm reduction over short-term customer satisfaction.
Operators licensed by the UKGC have invested heavily in compliance infrastructure. Larger companies have built dedicated responsible gambling teams, deployed machine learning models to identify at-risk customers, and restructured their bonus and promotional frameworks to comply with the Commission’s guidance on fair and transparent terms. The Commission’s 2021 decision to ban reverse withdrawals — a feature that allowed players to cancel a pending withdrawal and return funds to their account — is a specific example of how product design has been shaped by regulatory pressure. Research had identified reverse withdrawals as a feature disproportionately used by customers in distress.
For those seeking a structured overview of how the UKGC’s licensing conditions translate into practical obligations for operators and rights for players, the resource at https://www.betzella.com/ukgc-explained/ provides a detailed breakdown of the key regulatory requirements that licensed sites must meet, which is useful context for anyone evaluating whether a platform is genuinely compliant or merely nominally licensed.
The adaptation process has not been uniform across the industry. Smaller operators have faced disproportionate compliance costs, and several have exited the market or been acquired rather than invest in the required infrastructure. This consolidation has its own implications for competition and consumer choice, a tension the Commission has acknowledged without fully resolving. Meanwhile, the offshore market — operators holding licences from jurisdictions such as Curaçao or Malta but targeting UK players without a UKGC licence — continues to attract customers seeking fewer restrictions, raising questions about the effectiveness of any national regulatory framework in an internet-connected environment.
The UKGC’s trajectory over the past decade reflects a broader shift in how regulators think about consumer protection in high-risk markets. The Commission has moved from a model that assumed informed adult consumers could manage their own risk to one that accepts gambling products are capable of causing harm that consumers cannot always anticipate or prevent. Whether the specific interventions chosen — affordability checks, product restrictions, mandatory interaction — represent the right balance between protection and autonomy remains contested. What is not contested is that the Commission has fundamentally reshaped the environment in which UK gambling operates, and that the standards it has developed are increasingly referenced by regulators in other jurisdictions considering their own frameworks. Betzella’s analysis of the UKGC’s structure reflects how much the regulatory landscape has matured since the original 2005 Act, and how much further it is likely to evolve as the 2023 White Paper recommendations move through implementation. The story of player protection in the UK is, in many respects, the story of an institution learning — sometimes slowly, sometimes in response to public scandal — what it actually means to hold an industry accountable for the welfare of its customers.
Happy paddling!




Leave A Comment